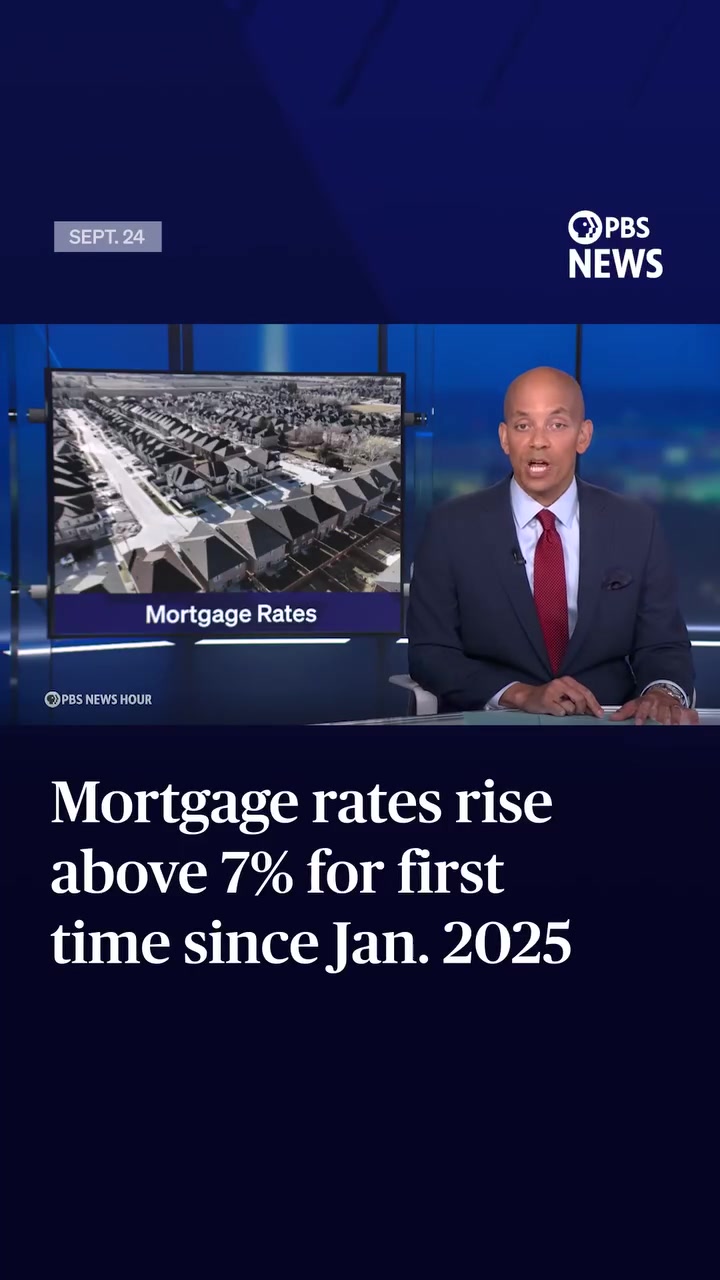
Jumping Over 7%
PBD News Hour reported on September 24, 2025 that mortgage interest rates hit seven percent. Freddie Mac pegged the 30-year fixed rate at 7.03%%
- the first such rate in more than 10 months. The news marked the end of a short reprieve for buyers: Rates had been trending down from 6% in 2025. But in January 2025 -- mortgages became more expensive.
The rise of the 7%
Mortgage rates are a financial rubber band: They pull the economy and housing in different directions.
- Cheap loans make housing cheaper and borrowers flush.
- Expensive mortgages price out some buyers, and drag down the housing market. When mortgage rates rise, home prices fall while the cost of borrowing increases. When mortgage rates fall, home prices rise, and lenders compete. Mortgage rates are affected by inflation and geopolitics. Rates started moving upward after Iran and Saudi Arabia went to war. Rates nationwide have been ascending. Freddie Mac, which reported a 30-year mortgage average of 7.03%, is a quasi-governmental agency. Its statements are not the final word on mortgage rates, but Freddie Mac has been around for years.
What Freddie Mac is saying
Freddie Mac's report on borrower lock-in offers the clearest explanation of the mortgage rate jumps. Rates remained unpredictable in 2025 due to geopolitical events. Freddie Mac underlined that borrowers keep benefits from low rates when they lock in. Freddie Mac’s interventions keep the American economy stable. Freddie Mac purchases mortgages from lenders, freeing up funds to make more loans. Freddie Mac then sells bonds backed by these mortgages. Mortgage lenders are exposed to greater risk when interest rates move because the value of a mortgage is inversely proportional to interest rates. When interest rates rise, the present value of the mortgage's future payments falls. Freddie Mac’s 30-year fixed rate mortgage is a key interest rate for the market. Freddie Mac is a mortgage giant backed by the U.S. government. It helps provide liquidity, stability, and affordability to the housing market. It was founded to help increase homeownership and stabilize the economy.
The Role of Inflation
Interest rates are the sword of inflation. When inflation rises, the central bank raises interest rates, to slow the economy.
- Borrowers then pay more to fund expenses.
- Savers make more on savings accounts. Savers get higher interest, slowing inflation. Higher rates put pressure on homebuyers. Banks are less likely to lend to risky borrowers when rates are high. When inflation is high, people buy more and more expensive goods and services. Prices rise.
Iran's war with Saudi Arabia
In January 2025, Iran and Saudi Arabia started war. The first thing that happened was that oil prices began to rise.
- Oil prices are a foundation of inflation. Oil was at $98/bbl on Jan 3rd. By Jan 31 it was at $110. Higher oil prices increase the cost of doing business. The cost of goods and services rises. When supply chains are disrupted, the cost of goods and services rises even more. Global investors and central banks reacted to the war. Oil is the world’s ‘black gold’. Oil prices rose by more than 10% after the hostilities started.
What buyers can do
Home buyers can find cheaper funding by:
- Loan type: Borrowers can expect to pay more to refinance a 30-year fixed-rate mortgage. Adjustable-rate mortgages start cheaper, but the rate adjusts each year.
- Curtail spending: Lowering monthly payments by reducing debt.
- Buy earlier in the process: Borrowers can lock in lower mortgage rates when they buy a home earlier in the year.
- Pay more up front: Borrowers can pay less per month if they pay more up front at closing.
Related deep dives
Similar reads based on topic and creator.
Recent articles
Fresh deep dives from the latest Reels we unpacked.
Comments
Be the first to comment.