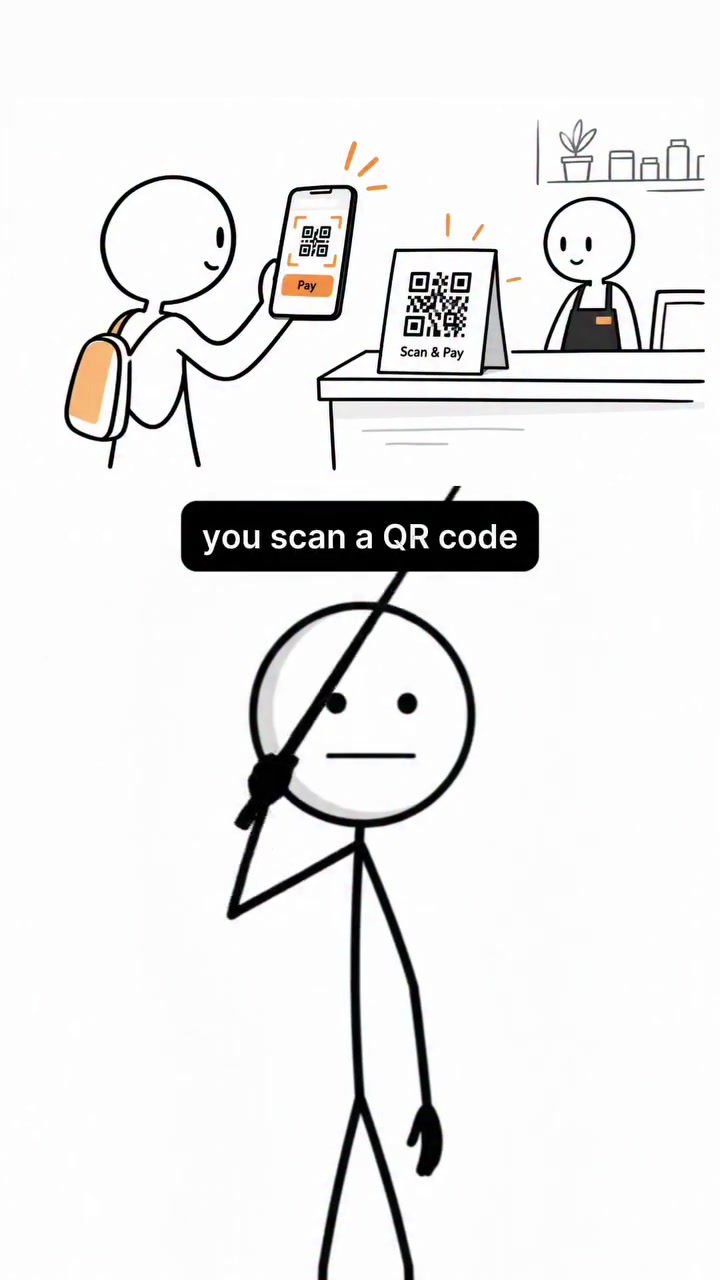
The Speed of QR Code Payments
Topping up a coffee tab or knocking off a friend's lunch bill becomes quicker than keying in a PIN. The exact moment when money zips from a smartphone to a merchant or peer cancels out landline speeds. You have a silent human hand doing the work, but the hand belongs to an engineer in India. The Unified Payments Interface (UPI) propels India towards digital transactions. In the midst of this function, the question arises: how do apps such as PhonePay or GooglePay make money if sending money mostly costs nothing? The trick lies in UPI. UPI brings users onto the platform, which allows building of financial and business tools. The ecosystem includes advertising, investments, loans, insurance, and bill payments.
The Platform that will Unify Banks into a Single App
UPI is built and regulated by the National Payments Corporation of India (NPCI), which is owned by government and private sector banks, according to the vision. It connects the rupees flowing from one bank to another. The technology is designed to be fast, underpinned by a network that handles transactions swiftly and securely. This technology connects banks, making seamless and secure transactions in real-time. UPI has become a convenient and quick alternative to traditional payment methods. This technology enhances financial inclusion by enabling transactions across diverse devices, from smartphones to feature phones.
Merchant Services Converge under UPI
UPI is more than a payment technology, UPI allows the apps to charge merchants fees for transactions initiated by their platforms. By building this ecosystem, apps like PhonePay and GooglePay create a bigger ecosystem. These companies can charge for merchant services, which can include billing and payment collection. These apps offer financial services like loans, investments, and insurance that make money for their ecosystem. Advertising also plays a role, the more users, the more valuable the platform for advertisers.
Business Tools
UPI can also charge financial and merchant services. It can add other tools to the app, for example, financial tools for businesses, to ensure large financial transactions are possible with ease. In this ecosystem, businesses can use UPI for transactions and services, and the app makes money through charges and fees. UPI charges a merchant discount rate, which is a fee paid by merchants to the platform for processing each transaction. This fee compensates the platform's service.
An Acceptable Payment Method
Paying using this ecosystem has become acceptable for many merchants in India. According to the data, the number of UPI transactions in India has increased significantly. UPI transactions have reached 93.4 million transactions in a single day in August 2023. In fact You don't need a merchant's account for a UPI transaction. Even a small vendor can use UPI, which makes it a mainstream payment option.
Integrating UPI into Your Financial Life
If UPI is not yet on your smartphone, setting up the app is simple. Here is what you can do:
- Assimilate banking: Open the UPI app on your smartphone, link your bank account, and create a Virtual Payment Address (VPA). This is what you share with others for receiving payments, giving you anonymity.
- Scan to Pay: Easily pay for goods and services by scanning the QR code on a merchant's screen. Tap "Pay" on your phone, enter the amount, and the transaction is done.
- Send Money: Enter the recipient's VPA or scan their QR code to send money instantly. By integrating UPI into your financial life, you gain both speed and security in your transactions.
The Future of Digital Transactions
The main benefits of this ecosystem are widely accepted by users across demographics. This ecosystem makes digital transactions accessible and safe, pushing India towards a cashless society.
Questions readers ask
What exactly is UPI and how does it work for everyday transactions?
UPI, or Unified Payments Interface, is a real-time payment system developed by the National Payments Corporation of India (NPCI). It allows users to transfer money instantly between bank accounts using a mobile app. For everyday transactions, you just need to link your bank account to a UPI app like PhonePe or Google Pay, create a virtual payment address, and you can send or receive money with just a few taps.
How do apps like PhonePe and Google Pay generate revenue if UPI transactions are mostly free?
While UPI transactions themselves are often free for users, apps generate revenue through the ecosystem they build around UPI. This includes charging merchants for transaction services, offering financial tools like loans and investments, and earning money through advertising. The more users and transactions, the more valuable the platform becomes for advertisers and financial services.
Can UPI be used for transactions other than peer-to-peer payments, such as paying for services or goods?
Absolutely. UPI is not limited to peer-to-peer payments; it's widely accepted for paying for services and goods. Many merchants, from small vendors to large businesses, accept UPI payments, making it a versatile and convenient option for various transactions. You can pay for everything from a cup of coffee to utility bills using UPI.
What are the benefits of using UPI for merchants, especially small vendors?
For merchants, UPI offers several benefits. It's a cost-effective way to accept payments without needing a separate merchant account. Additionally, UPI transactions are processed in real-time, ensuring faster access to funds. This makes it an attractive option for small vendors who want to streamline their payment processes and reduce transaction costs.
Is UPI the only digital payment method in India, or are there other alternatives available?
UPI is one of the most popular digital payment methods in India, but it's not the only one. Other alternatives include mobile wallets like Paytm, credit and debit card transactions, and traditional net banking. However, UPI stands out due to its real-time transaction capabilities, wide acceptance, and integration with various financial services.
What are the potential risks or drawbacks of using UPI for financial transactions?
While UPI is generally secure, there are potential risks to be aware of. These include the risk of fraud, especially if your UPI ID or mobile device is compromised. Additionally, there can be technical glitches or delays in transactions, although these are relatively rare. It's important to use strong authentication methods and keep your app updated to minimize these risks.
Can foreign visitors use UPI for transactions in India, or is it limited to Indian residents only?
UPI is primarily designed for Indian residents and requires an Indian bank account. Foreign visitors may find it challenging to use UPI for transactions. However, some international banks have partnerships with Indian banks that might offer similar services. For most visitors, using international credit or debit cards or mobile wallets like PayPal might be more convenient.
Related deep dives
Similar reads based on topic and creator.
Recent articles
Fresh deep dives from the latest Reels we unpacked.
Comments
Be the first to comment.